The 28/36 Rule Explained: How to Budget Using the 28/36 Rule
Written by MasterClass
Last updated: Sep 8, 2021 • 3 min read
When shopping for a new house, some prospective homeowners keep a limit on how much of their monthly income goes to housing expenses. The 28/36 rule is one technique used to stay within a reasonable limit.

Learn From the Best
What Is the 28/36 Rule?
The 28/36 rule is a personal finance principle that caps how much of a person's gross monthly income should go to housing costs and how much should go to monthly debt payments. There are two core tenets of the 28/36 rule.
- No more than 28 percent of your gross monthly income should go to monthly housing costs. This goes beyond a monthly mortgage payment to include all costs related to holding title on a home. Sometimes the ratio of housing expenses to your total income is called the PITI ratio, where PITI stands for principal, interest, taxes, and insurance.
- No more than 36 percent of your gross monthly income should be spent on total debt and loan payments. This total monthly debt includes conventional mortgages, but it also includes other forms of borrowing like credit card debt and personal loans.
How to Apply the 28/36 Rule
The 28/36 rule is applied to financial decisions regarding budgeting and taking on new debt. First-time homebuyers and other types of borrowers sometimes break down the 28/36 rule into two types of ratios: a front-end ratio and a back-end ratio.
- Front-end ratio: The front-end ratio of the 28/36 rule is a ratio of your total housing expenses to your total income before taxes. According to the rule, that ratio should not be greater than 28/100. For most homeowners, the primary contributor to housing costs is their monthly mortgage payment, but housing costs also include homeowners insurance, property taxes, and homeowners association (HOA) dues. They do not include one-time costs at the time of purchase such as closing costs, a credit report, and one-time mortgage insurance. They also do not include everyday household expenses you must pay regardless of homeownership, such as groceries and utilities. Your front-end ratio will vary depending on the size of your down payment, the size of your mortgage loan, your credit score, and prevailing interest rates charged by mortgage lenders.
- Back-end ratio: The back-end ratio of the 28/36 rule is a ratio of your total debt expenses to your total income. According to the rule, the debt-to-income ratio (DTI ratio) should not be greater than 36/100. For most homeowners, a home loan represents the largest share of their monthly debt. However, many other factors can contribute to your back-end ratio including credit card debt, student loans, car loans, VA loans, personal loans, alimony payments, and child support.
Example of a Budget Using the 28/36 Rule
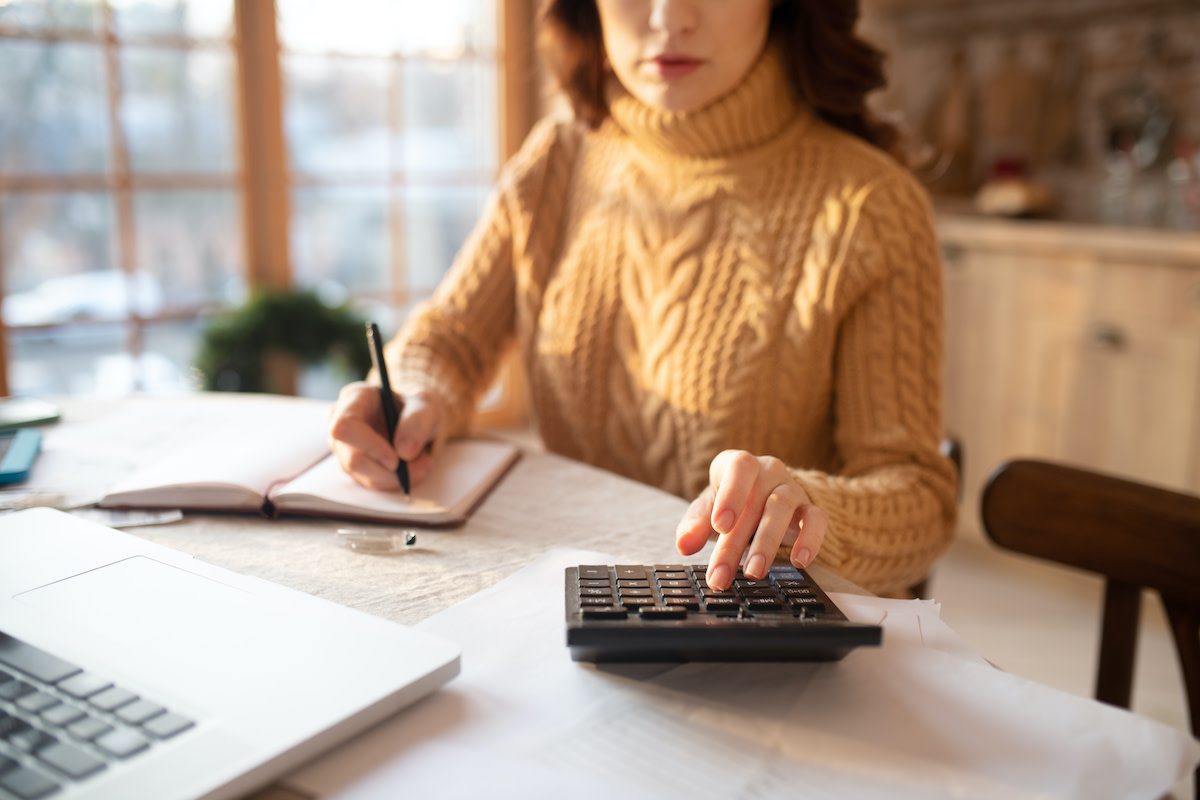
Imagine you have an annual income of $48,000 based on a W2 employee salary and extra cash from some odd jobs. This breaks down to a monthly pre-tax income of $4,000. With this in mind, you would have the following limits for your monthly real estate expenses and debt expenses.
- A maximum of $1,120 per month on housing expenses: Twenty-eight percent of $4,000 is $1,120. To stay within the 28/36 rule, you would have to spend no more than that amount on mortgage payments, property taxes, HOA fees, and related costs.
- A maximum of $1,440 on all debt payments: Thirty-six percent of $4,000 is $1,440. To stay within the 28/36 rule, you would have to spend no more than that amount on homeownership, credit card interest, and various forms of loans.
A Note on Real Estate Investment
All investments, including real estate investments, come with inherent risks which may involve the depreciation of assets, financial losses, or legal ramifications. The information presented in this article is for educational, informational, and referential purposes only. Consult a licensed real estate or financial professional before making any legal or financial commitments.
Ready to Learn the Ins and Outs of the American Housing Market?
All you need is a MasterClass Annual Membership and our exclusive video lessons from prolific entrepreneur Robert Reffkin, the founder and CEO of the real estate technology company Compass. With Robert’s help, you’ll learn all about the intricacies of buying a home, from securing a mortgage to hiring an agent to tips for putting your own place on the market.

Business
Daniel Pink’s ABC’s of Selling: Inside the 3 Key Sales Qualities
Dec 10, 2021
Business
4 Types of Innovation
Dec 13, 2022
Business
How Odd-Even Pricing Works: Psychology of Odd-Even Pricing
Mar 30, 2022
Business
Internship Guide: How to Find an Internship
Jul 15, 2021
Business
Cottage Industry Definition: 4 Examples of Cottage Industries
Oct 31, 2022
Business
Branded Content Definition: 3 Content Marketing Examples
Jan 4, 2022
Other articles
New England Clam Chowder: 4 Tips for Making Chowder
Oct 23, 2026
Claude Debussy: A Guide to Claude Debussy’s Life and Music
Jun 25, 2021
How to Play Basketball: Explore the Basics of Basketball
Jun 7, 2021
How to Write a Horror Story in 7 Steps
Dec 8, 2021
Wine 101: What Is Barrel Aging? Understanding the Barrel Aging Process in Winemaking and the Difference Between Steel and Oak Barrels
Sep 2, 2022
Heavy Metal Music Guide: A Dive Into Heavy Metal Music
Jul 15, 2021